Greetings from Scotland! Over the past week, we've been making the most of the school break by travelling to this beautiful part of the world. We've explored Edinburgh and Glasgow, enjoyed a road trip through the spectacular Scottish Highlands, and even made it all the way to the legendary Loch Ness in our rental car.
One of the highlights of the trip was the 50th anniversary conference of the Association of Translation Companies (ATC), attended by our CEO at Caulingo. Meanwhile, I took a somewhat different approach to exploring the local economy, spending time shopping at Primark and Deichmann, while occasionally exchanging handshakes with fellow European founders over breakfast.
And, naturally, I couldn't resist combining travel with investing. I picked up a few fractional shares of IHG (InterContinental Hotels Group), the company behind the hotels we stayed at during our Scottish adventure — Holiday Inn Express in Edinburgh and voco in Glasgow.
A little sightseeing, a little shopping, a little business networking, and even some stock accumulation along the way.
Stock Market Overview
It has been another mixed week for US stock markets, with renewed selling pressure in technology and AI-related stocks contrasting with relative strength in more traditional sectors.
The biggest pressure came from technology stocks, particularly semiconductors, as investors continued questioning elevated AI valuations and the sustainability of heavy capital spending. Meanwhile, healthcare, consumer staples and financial stocks showed greater resilience.
For our dividend and options portfolio, the environment was relatively manageable. We finished the reporting week with a modest gain, although several outstanding short option positions continued to weigh on overall performance.
The coming week could prove more eventful, with the Federal Reserve's interest rate decision and quarterly earnings from several major US companies, including Microsoft, Alphabet, Amazon and Bristol Myers Squibb.
Dividend Stock Portfolio Performance
As of October 23, 2026, our options-selling-powered dividend stock portfolio stood at $13,510, marking a weekly increase of 0.40% compared with the previous week.
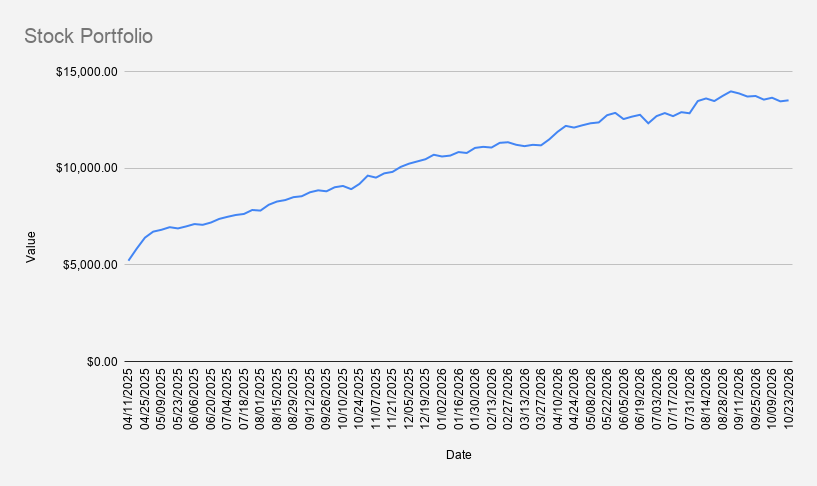
Year to date, our portfolio is up 34.58%, comfortably outperforming the S&P 500's reported 11.47% gain over the same period.
Over the past few weeks, our portfolio has remained largely flat, struggling to break through the $14,000 milestone. The main drag on performance has come from two longer-dated put option positions rather than the underlying stock holdings themselves.
Nevertheless, we remain cautiously optimistic about a potential rebound as we approach year-end. Our $15,000 portfolio target remains on the radar, although achieving it would require an exceptionally strong final two months of the year.
Besides purchasing a few fractional shares, we also rolled our weekly BMY put option forward and down for a net credit, lowering our strike price while collecting additional premium.
With Bristol Myers Squibb scheduled to report quarterly earnings on October 29, just one day before our October 30 put expiration, we expect increased volatility in the stock. Hopefully, the earnings reaction will be positive, but we are prepared to manage the position if the market moves against us.
Current Open Options Positions
- BMY OCT 30, 2026: $59 Cash-Secured Put
- BMY NOV 20, 2026: $55/$50 Credit Spread
- NFLX NOV 20, 2026: $85/$105 Bear Call Spread
- BAC DEC 18, 2026: $57.5/$60 Bear Call Spread
- LHA (Frankfurt) DEC 18, 2026: €7 Cash-Secured Put
- BAC MAR 19, 2027: $55 Short Put
- NFLX DEC 17, 2027: $64 Short Put
- NVDA JAN 21, 2028: $130 Covered Call
Our open positions now span several expiration dates, ranging from near-term options to long-dated contracts extending into 2028.
Among our open positions, Lufthansa continues to put pressure on portfolio performance. If the stock fails to rebound, we may consider rolling the €7 cash-secured put forward and down in the coming weeks to reduce our potential assignment price, ideally while collecting additional premium.
We will also pay particular attention to our BMY positions. The October 30 $59 put and November 20 $55/$50 credit spread both carry downside exposure to the same underlying stock, making the upcoming earnings announcement especially relevant.
Our NFLX November bear call spread also deserves monitoring, particularly if technology stocks rebound sharply after recent weakness. Meanwhile, our longer-dated NFLX and BAC short puts remain positions to evaluate in terms of capital requirements, assignment exposure and potential rolling opportunities.
Weekly Options Premium
Our reported options premiums collected during Week 81 reached $54. While below some of our stronger weeks, the income continues to support gradual portfolio accumulation.
Our outstanding margin debt now stands at approximately $2,403, slightly higher than a week ago, partly reflecting additional share purchases.
In theory, if we directed the entire $54 in weekly options premiums toward paying down margin debt, it would take approximately 45 weeks to eliminate the remaining balance.
Of course, this assumes consistent weekly premium collections, no additional borrowing, and no interest expenses or trading losses. Real life is rarely that straightforward.
This week, we added:
- 0.1 share of BMY
- 0.2 share of IHG
- 2 shares of NIO
- 1 share of NU
These small purchases are part of our gradual accumulation strategy. They won't transform the portfolio overnight, but over time, they should help us build larger positions and potentially open new opportunities for covered call selling.
Bottom Line and What We're Watching Next Week
Another relatively quiet week for our portfolio, with a 0.40% gain bringing NAV to $13,510. We collected $54 in options premiums, continued accumulating fractional shares and successfully rolled our challenged BMY put to a lower strike for additional credit.
While our underlying stock holdings have generally remained resilient, several outstanding options positions continue to limit overall portfolio progress. As we approach the final two months of 2026, the immediate objective remains to break through $14,000, while keeping our more ambitious $15,000 year-end target in sight.
Next week, our attention will be focused on:
- BMY earnings on October 29: Our most immediate portfolio-specific event. We will monitor the $59 cash-secured put expiring October 30 and the November $55/$50 credit spread. A positive earnings reaction could provide welcome relief, while further weakness might require another adjustment.
- Lufthansa and the €7 put: We will watch for signs of a sustained recovery. If the stock remains under pressure, rolling the December position to a lower strike and later expiration may become an option, depending on pricing and available credit.
- NFLX and BAC options exposure: The November NFLX bear call spread could become more challenging during a technology rebound. We will also monitor our December BAC bear call spread, particularly if financial stocks continue outperforming.
- Federal Reserve and major technology earnings: The October 28 Fed decision, together with Microsoft, Alphabet and Amazon earnings, could influence broader market sentiment and volatility, including the outlook for our technology-related positions.
- Margin and portfolio milestones: At approximately $2,403 in outstanding margin debt, we will continue balancing new stock purchases with options income and risk management. The $14,000 milestone remains our immediate objective.
For now, our strategy remains unchanged: sell options, collect premiums, accumulate quality stocks and manage challenged positions patiently. The market may offer better opportunities toward year-end, but there is no reason to force trades simply to reach a portfolio milestone.
Slow and steady. Another week of building the portfolio, one trade and one fractional share at a time.