One possibility is to sell a bear call spread above the market while continuing to hold the short put. The additional credit can reduce the position's cumulative cost, but it does not eliminate the downside risk of the put. Instead, it introduces a second risk: the stock may recover strongly and challenge the short calls.
I am dealing with exactly this situation in a Netflix, Inc. (NASDAQ: NFLX) position. This article uses that real portfolio case to explain when a bear call spread may be useful as an income overlay, what it does not protect against, and how I think about delta, expiration, position size and management.
My NFLX Position: The Real Trade Behind This Example
In May 2026, I opened an NFLX position using put credit spreads. The original idea was straightforward: collect option premium while keeping the maximum loss defined with protective long puts.
As NFLX weakened, I changed the structure. I removed the protective legs, leaving much more direct exposure to the short put. That increased the premium collected and gave the trade more time, but it also materially increased the downside risk.
Following Netflix's July 2026 earnings report, the stock declined sharply. NFLX closed July 17 at approximately $68.95, down 7.26% for the session.
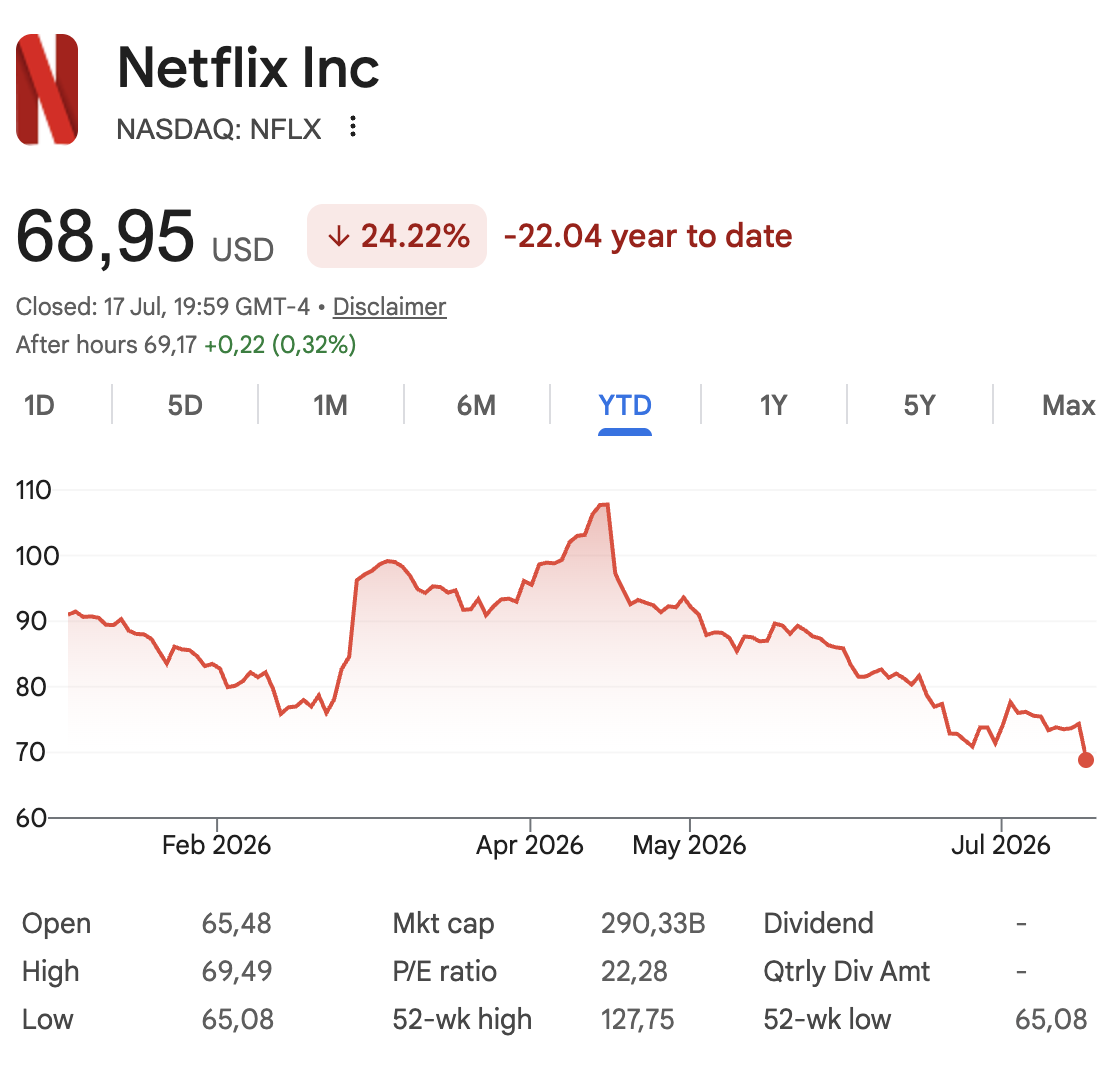
I eventually rolled the short put farther into the future, to a December 2027 expiration. That reduced the immediate pressure and lowered the strike, but it did not erase the loss. It exchanged a near-term problem for a much longer commitment to NFLX.
I documented the weekly portfolio context separately in $147.60 in Weekly Options Premium Despite Netflix's 10% Earnings Drop.
The next question was whether shorter-dated bear call spreads could generate additional premium while the long-dated put remained open.
The General Problem: Managing a Challenged Short Put
A short put is fundamentally bullish. The position benefits when the stock stays above the strike, rises, or at least stops falling.
Once the stock falls substantially below the original thesis, several choices become possible:
- Close the position and accept the loss.
- Roll the short put to a later expiration or different strike.
- Accept assignment and own the shares.
- Add another options position intended to collect additional premium.
The last choice is where a bear call spread can enter the picture.
It is important, however, to understand what problem the new position is actually solving.
What a Bear Call Spread Adds
A bear call spread normally consists of:
- Selling an out-of-the-money call.
- Buying a higher-strike call with the same expiration.
- Collecting a net credit.
- Accepting a defined maximum loss if the stock rises through both strikes.
The long call limits the theoretical loss of the call spread itself.
Against a challenged short put, the purpose of the call spread is not necessarily to become bearish on the stock. It can instead be used as an income overlay: collect additional premium while waiting for the underlying position to improve.
Why This Is Not a True Hedge
This distinction is critical.
The short put and the bear call spread respond differently to large price moves.
- Short put: bullish, with increasing downside exposure as the stock falls.
- Bear call spread: bearish to neutral, with defined risk if the stock rises.
Combining them can create a position that performs best when the stock remains inside a broad range:
- Above the most dangerous area for the short put.
- Below the short-call strike.
- With enough time decay for both option structures to lose extrinsic value.
The bear call spread may generate income when the stock trades sideways, rises gradually or continues drifting lower.
But it does not directly protect the short put from a severe decline.
I therefore would not describe this as hedging the downside of the put. A better description is:
A defined-risk income overlay intended to reduce the cumulative cost of a challenged bullish position.
That wording matters because the new trade introduces its own risk rather than eliminating the original one.
What the Combined Position Is Doing
Position | Directional effect | Main risk |
|---|---|---|
Short put | Bullish / positive delta | Large downside move |
Bear call spread | Neutral to bearish / negative delta | Strong upside move |
Combined position | More range-dependent | Either side can become challenged |
The result may look balanced at first, but the balance is not stable.
Delta changes as the stock moves, time passes and implied volatility changes.
Before Adding a Bear Call Spread, Ask These Questions
- Do I still want bullish exposure to the stock?
- Would I still be comfortable owning the shares if assigned on the put?
- Am I adding the call spread because it improves the economics, or because I do not want to admit the original trade went wrong?
- How much additional loss can the call spread create?
- What happens if the stock rebounds sharply?
- Is the available premium large enough to justify the additional complexity?
- Can I actively monitor both sides of the position?
If the answer to those questions is unclear, adding another options structure may create more problems than it solves.
Choosing the Short-Call Delta
For my NFLX position, I was considering relatively low-delta short calls because I wanted room for the stock to recover.
Short-call delta | How I think about it |
|---|---|
0.08–0.12 | More conservative, lower credit, more room for recovery |
0.13–0.17 | Balanced range I would examine first |
0.18–0.25 | More premium, but materially greater upside risk |
Above 0.25 | Increasingly aggressive for a volatile single stock |
In my case, the 0.12–0.18 delta area appeared more reasonable than selling calls close to the money.
This is not a universal rule. The important principle is that the strike should reflect the purpose of the overlay.
If the goal is to allow the stock to recover while collecting some premium, selling a high-delta call may defeat that purpose by creating another challenged position after only a modest rebound.
Selecting the Long Call
The higher-strike long call defines the maximum risk of the spread.
One simple approach is to use a fixed-width spread.
For example:
- Sell one call.
- Buy another call $5 above it.
- Collect a net credit.
The theoretical maximum loss is:
Spread width − credit received
A $5-wide spread sold for $0.80 would have a theoretical maximum loss of:
$5.00 − $0.80 = $4.20 per share, or $420 per contract.
Another method is to select both strikes by delta, for example selling around 0.15 delta and buying a farther out-of-the-money call around 0.05–0.08 delta.
I generally prefer fixed-width spreads in smaller portfolios because the maximum loss is easier to understand before entering the trade.
How I Think About Expiration
For the NFLX overlay, I was considering approximately 30–60 days to expiration.
The reasoning was not that this range is universally optimal. It was that it offered a reasonable compromise between premium collection and management flexibility.
- Enough time value to produce a meaningful credit.
- Less extreme gamma risk than very short-dated spreads.
- More time to adjust if the stock begins moving toward the short strike.
- More flexibility to select a strike well above the current market.
Very short-dated spreads may decay quickly, but the position can also become difficult to manage quickly.
A sharp three-day rally can overwhelm a seven-day credit spread before there is much time to react.
For my own case, a tentative framework was:
- Open around 40–50 DTE.
- Monitor more closely around 21 DTE.
- Avoid holding a challenged spread into its final few days.
- Avoid unintentionally carrying the spread through earnings.
Position Size Matters More Than the Premium
One of the easiest mistakes in a recovery trade is sizing the new position according to how much money you want to recover.
I think the better question is:
How much additional loss can I tolerate if the adjustment itself goes wrong?
A standard U.S. equity option contract ordinarily represents 100 shares.
That can create a large mismatch between the size of the stock position and the size of the options exposure.
In my case, the sensible starting point would be no more than one narrow call spread for each short put.
The objective is not to recover the entire loss quickly. Trying to do that can encourage selling strikes too close to the market, using spreads that are too wide or taking more risk than the original portfolio can support.
The Biggest Risk: Strategy Drift
This is probably the most important lesson from my NFLX position.
The trade evolved through several stages:
- A defined-risk put credit spread.
- A short put after removing the protective leg.
- A much longer-dated short put after rolling.
- A possible bear call spread overlay.
- Potential stock purchases or delta hedging.
Each adjustment can look rational when considered individually.
Together, however, they can create a position that no longer resembles the trade originally opened.
This is strategy drift.
An adjustment is not automatically an improvement. Every additional leg should solve a clearly defined problem.
What a Bear Call Spread Does Not Do
- It does not erase the existing short-put loss.
- It does not cap the downside risk of the short put.
- It does not guarantee enough premium to recover the loss.
- It adds another source of risk.
- It can lose money during a strong stock rebound.
- Rolling the spread does not erase a prior loss.
A roll should be viewed economically as two transactions: closing one position and opening another.
A Practical Management Framework
Entry
- Choose a defined-risk call spread.
- Use a short-call strike far enough away to preserve the original thesis.
- Keep maximum loss small relative to the overall portfolio.
- Avoid earnings exposure unless it is intentional.
Profit management
In my NFLX case, I would consider closing after capturing approximately 40–60% of the original credit rather than waiting for every remaining dollar.
Closing early releases risk and allows the next cycle to be evaluated independently.
If the stock approaches the short call
Possible responses include:
- Close the spread for a controlled loss.
- Roll upward and farther out if the economics make sense.
- Reduce the position size.
- Use shares as a partial delta offset.
- Accept the predefined maximum loss.
None of these actions should be automatic.
If the stock continues falling
The bear call spread may become profitable, but the short put can lose substantially more than the spread earns.
This is another reason the call spread should not be described as a complete hedge.
Advanced: Using Shares as a Delta Hedge
A more advanced possibility is to use shares to offset part of the negative delta created by a challenged bear call spread.
Suppose the combined position has a net delta of approximately –25.
The portfolio would then behave, for a small move in the stock, approximately like being short 25 NFLX shares.
Buying around 25 shares could move the position closer to delta neutral at that moment.
But delta hedging is dynamic.
As the stock moves:
- The short call's delta changes.
- The long call's delta changes.
- The put's delta changes.
- The amount of stock needed for the hedge changes.
This introduces additional trading costs and timing risk. It can also lead to repeatedly buying shares after rallies and selling them after declines.
For that reason, I view share-based delta hedging as an advanced portfolio-management tool rather than a simple repair technique.
When I Would Stop Using the Overlay
I would reconsider the strategy if:
- My view of the stock became strongly bullish.
- The stock began a powerful recovery.
- Conservative call strikes no longer offered meaningful credit.
- Bid-ask spreads made adjustments expensive.
- The options exposure became too large relative to the portfolio.
- Repeated spread losses exceeded the premium generated.
- I was no longer willing to actively monitor the position.
- Simply owning or closing the stock exposure became easier than maintaining the derivatives structure.
The purpose of an adjustment is to improve the economics of a position, not to defend the original decision indefinitely.
A Checklist for Your Own Position
Before applying this idea to another stock, I would work through the following checklist:
- Do I still believe in the original bullish thesis?
- Would I accept assignment on the short put?
- What is my maximum remaining downside on the put?
- What new maximum loss does the call spread introduce?
- What happens if the stock rallies 10%, 20% or more?
- Does the premium justify the complexity?
- Is the options market liquid enough to manage the spread efficiently?
- Is there an earnings report or other major event inside the expiration?
- Do I have predetermined rules for closing, rolling or accepting a loss?
What I Learned From the NFLX Position
The biggest lesson is not that bear call spreads are a clever way to repair losing puts.
It is that every adjustment changes the risk profile.
My NFLX trade began as a defined-risk position. Each subsequent modification increased the number of decisions required to manage it.
The bear call spread may provide additional premium, but that premium is compensation for accepting another risk.
If NFLX remains relatively stable, the overlay may gradually improve the economics of the position.
If NFLX falls sharply, the put remains the dominant risk.
If NFLX rebounds sharply, the call spread can become the problem instead.
Bottom Line
A bear call spread can be used as a defined-risk income overlay against a challenged short put, but it should not be confused with a true downside hedge.
In my NFLX case, I was considering relatively conservative short-call deltas, roughly 30–60 DTE, modest position sizing and active management before expiration.
Those parameters belong to this particular portfolio situation. The more general lesson is more important:
Do not add an adjustment simply because a trade is losing. Add it only when you understand exactly which risk it reduces, which new risk it creates, and how much additional loss you are willing to accept.
The objective is not to force a losing trade back into profit at any cost.
It is to manage the portfolio without allowing the repair strategy to become more dangerous than the original position.
Disclosure: This article documents my personal trading process and is intended for educational purposes. It is not financial advice. Options involve substantial risk and are not suitable for every investor.